Investors seeking broad exposure to the U.S. stock market typically choose between two options: the S&P 500 index or a total market index. Over the long run, the difference between them is unimportant. Yet many investors still find themselves overanalyzing the choice. Both options hold only U.S. companies, so international stocks are a separate decision. This article breaks down the key differences, saves you some research time, and lays out the case for each approach so you can decide which fits you best.
In a nutshell, index investing is a passive investment strategy that seeks to capture the average market return by owning index funds rather than attempting to beat the market through individual stock selection or active fund management. Index investors accept that consistently picking winning stocks over long periods is extremely difficult, and the evidence supports them: year after year, the SPIVA Scorecard finds that more than 90% of actively managed U.S. large-cap funds underperform the S&P 500 over the previous 20 years. Index investors are therefore content with earning the market return, relying on the power of compounding rather than outsized bets to build wealth.
The approach is simple and effective, but it still requires one key decision: whether to capture that market return with the total market or the S&P 500.
Before diving into the specifics of the total market and the S&P 500, it’s helpful to understand market capitalization. When I refer to the “size” of a company, I’m talking about its market capitalization (or market cap), which is calculated by multiplying the number of shares outstanding by the share price. Both the S&P 500 and the total market indexes weight their holdings by market cap, adjusted for float — meaning only shares available to the investing public count toward a company’s weight (not shares held by insiders or governments).
Overview
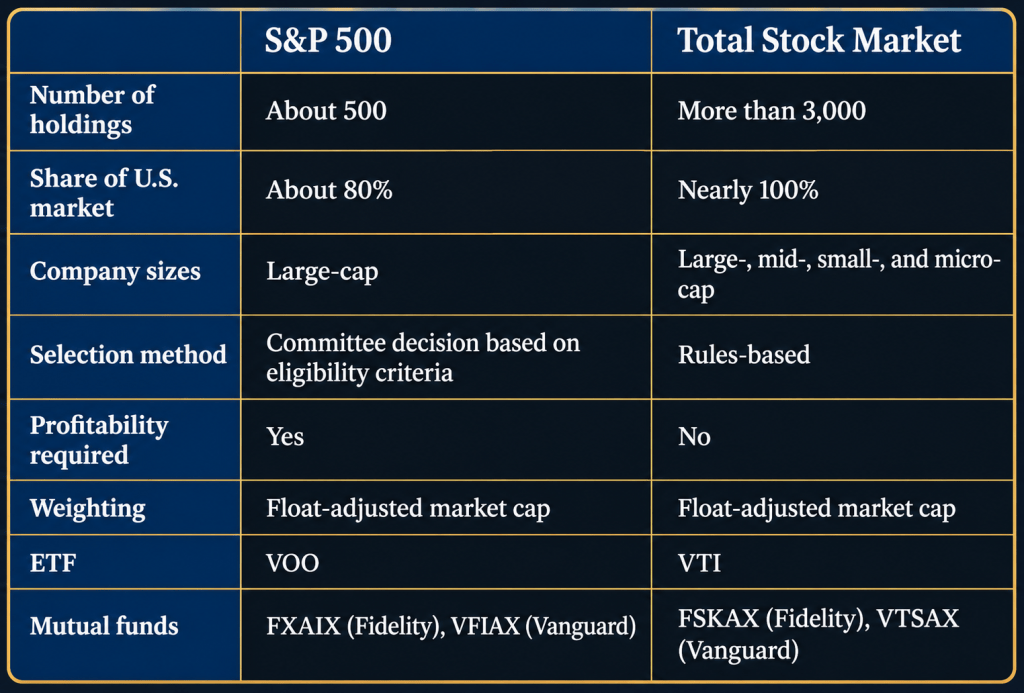
The S&P 500 is basically (but not exactly) the 500 largest companies in the United States. It is maintained by S&P Dow Jones Indices, part of S&P Global (which also provides credit ratings). The goal of the S&P 500 is to capture about 80% of the stock market’s total value, and the amount it captures can vary from 75%–85% at any given time. However, the index is not purely based on size. To be eligible, a company must be U.S.-based, meet a minimum market cap threshold (which S&P periodically adjusts), have adequate liquidity and public float, and demonstrate financial viability through positive earnings in both the most recent quarter and the trailing four quarters combined. Even then, membership is not automatic. A committee ultimately selects the S&P 500 companies, aiming to maintain balanced representation across sectors of the U.S. economy. As a result, a company can meet all stated criteria and still be left out, as Tesla was: it became eligible in mid-2020 but was passed over by the committee that September and not added until December 2020.
At one time, the S&P 500 served as a reasonable proxy for the overall U.S. stock market. Over time, however, it became possible to capture nearly 100% of the market’s total value through total market indexes. While there is only one S&P 500, multiple total market indexes exist.
The selection criteria in the next paragraph apply specifically to the Dow Jones U.S. Total Stock Market Index (tracked by Fidelity’s FSKAX) and the Morningstar U.S. Total Market Index (tracked by Vanguard’s VTI and VTSAX). Selection criteria for other total stock market indexes may vary slightly but will be very similar.
Inclusion in a total market index is largely mechanical. Companies must meet basic requirements for things like being publicly traded, U.S.-based, liquid, and sufficiently available for investors to trade. Unlike the S&P 500, the total market index does not require companies to meet minimum size or profitability standards. As a result, it includes the large companies in the S&P 500 along with thousands of mid-, small-, and micro-cap companies, more than 3,000 holdings in total. Because both indexes weight holdings by market cap, the S&P 500 companies make up roughly 80% of a total market fund, and those thousands of smaller companies make up the remaining 20% or so.
The Case for the Total Stock Market
A total market fund holds nearly every publicly traded U.S. company in proportion to its size, so it delivers the U.S. stock market’s return itself rather than a large-cap subset of it. There are no committee decisions or size and profitability screens to evaluate: a single fund represents the entire domestic equity market.
A total market index provides broader exposure to mid- and small-cap companies, which have historically outperformed large-cap stocks over long periods of time, though not in every decade. Owning smaller companies also allows investors to capture the full growth of the next major success before it becomes widely known.
Total market indexes also use an objective, rules-based methodology, whereas the S&P 500 relies on committee discretion. Investors who prefer not to depend on a committee’s judgment may see this as an advantage, particularly given the well-documented benefit a stock receives from inclusion in the S&P 500, which makes that discretion consequential.
The additional holdings in a total market index naturally reduce concentration in the largest companies, shifting portfolio weight away from mega-caps. Large, popular companies are more susceptible to valuation-driven bubbles, and reducing concentration in them can lessen the impact of a bubble unwinding by lowering exposure to extreme valuations. The total market held up better in the infamous “Lost Decade” of 2000-2009, compounding at an annual rate of -0.28% versus -1.03% for the S&P 500. That said, the effect is modest because mega-caps dominate both indexes.
Because total market indexes have no profitability requirements, they also allow investors to own companies that may be temporarily distressed but later recover and thrive. Owning the entire market also removes the need to guess which company will be the next big winner (and eliminates FOMO, fear of missing out), since you already own them all.
The Case for the S&P 500
Owning 500 companies already provides substantial diversification, and expanding to more than 3,000 companies adds little additional diversification benefit. In fact, research discussed in Burton Malkiel’s A Random Walk Down Wall Street has shown that owning as few as 50 stocks can eliminate most company-specific (non-systematic) risk.
Large, established companies have historically been less volatile than small ones, and the S&P 500’s profitability screen keeps unprofitable companies from being added. Because small caps carry more risk, an index made up entirely of large companies may experience modestly smaller declines in some market environments, which can matter to investors nearing or already in retirement. The difference is modest, though, since S&P 500 companies make up roughly 80% of the total market.
The S&P 500 is also the most widely used benchmark for the U.S. stock market, making its performance easy to find, compare, and track against. It is offered by nearly every fund provider and is commonly available in employer retirement plans, which can make it more accessible than a total market fund inside some 401(k)s.
The S&P 500’s committee-driven approach can also be viewed as a benefit: in addition to the financial viability screen, the committee aims to keep the index balanced across sectors of the economy.
The S&P 500 also has the endorsement of Warren Buffett, one of the most respected investors in history. Buffett has repeatedly recommended it and has even specified in his will that 90% of his wife’s inheritance be invested in an S&P 500 index fund, with the remaining 10% allocated to short-term Treasury bonds.
Conclusion
I personally prefer the total stock market, but you won’t go wrong buying and holding either option long term. Because the S&P 500 represents roughly 80% of the total stock market, the two indexes overlap heavily and have a 0.99 correlation, meaning they move almost in lockstep. As a result, their long-term returns have been very close.
Over shorter periods, one will outperform the other depending on which segment of the market is leading. When small-cap stocks outperform, as they did in the 2000s, the total stock market tends to have a slight edge. When large-cap stocks lead, as they did in the 2010s, the S&P 500 tends to come out ahead.
There is generally no reason to hold both in the same account, since they overlap so heavily and combining them simply tilts your portfolio toward large caps. One exception is a taxable account, where some investors hold one fund and swap into the other when harvesting tax losses. Because the two track different indexes, the swap is generally considered to avoid the wash-sale rule, though it’s worth confirming with a tax professional. Otherwise, choose the approach that aligns with your preferences and stay the course.
Discover more from Bryant Quick
Subscribe to get the latest posts sent to your email.

