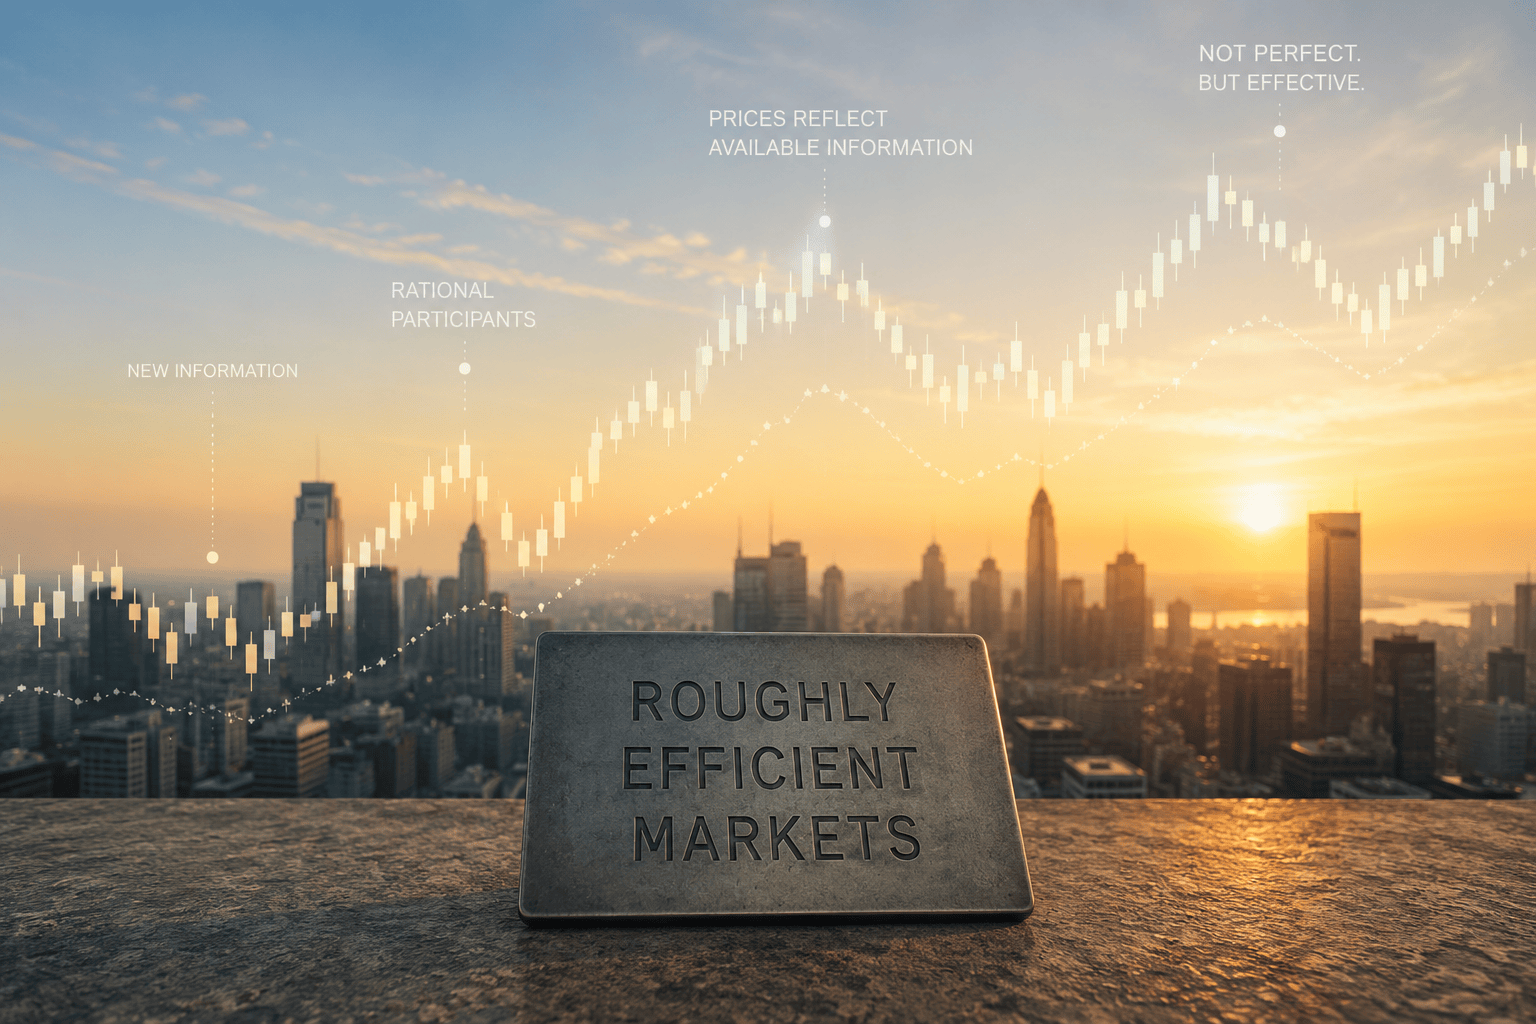
The Efficient Market Hypothesis (EMH) is a foundational concept in finance and is widely taught in academia. At its core, EMH holds that security prices rapidly incorporate all publicly available information, making it extremely difficult for investors to consistently achieve above-average returns. I believe this framework is largely correct but often taken too far. Below, I’ll cover what I think EMH gets right, where it overreaches, and why the practical conclusion for most investors is the same either way.
EMH rests on two fundamental ideas:
- Publicly available information is quickly reflected in stock prices
- In an efficient market, there are no possibilities for earning outsized returns without taking on outsized risk.
What EMH Gets Right
There’s little doubt that new information is incorporated into market prices quickly. And the second idea holds up too, as long as it’s understood correctly. Competition among investors is intense, so opportunities for extraordinary gain rarely last. Burton Malkiel describes it this way:
“In an efficient market, competition will ensure that opportunities for extraordinary risk-adjusted gain will not persist.”
“It is possible that the stock market could fail fully to reflect some news event…Therefore, it is probably useful to think of the stock market in terms of “relative” rather than absolute efficiency…it is unrealistic to require our financial markets to be perfectly efficient in order to accept EMH.”
Burton Malkiel
That is the version I accept: efficiency as a matter of degree rather than an absolute. Some of the best-known investors of all time agree.
“To me it’s almost self-evident…the market is generally, fairly efficient.”
Warren Buffett
“Hard form efficient market theorists—they’re an embarrassment to the scene…The people who think the market is reasonably efficient or roughly efficient are absolutely correct.”
Charlie Munger
Where EMH Gets Taken Too Far
The trouble starts when a reasonable framework gets stretched into an absolute. There are three places this happens.
1. Hard is not the same as impossible
The extreme version of EMH says it is impossible to beat the market. Taken that far, it gets treated almost like a law of nature, similar to gravity, as if some invisible force prevents anyone from outperforming.
In reality, beating the market is hard because mispricings get exploited quickly. When an opportunity for extraordinary gain appears, someone takes advantage of it, which means someone does beat the market. Outperformance isn’t impossible. Sustained outperformance is rare because the competition is intense and never stops.
“[Efficient market hypothesis] It’s roughly right. It’s just the very hard form…they believed it was impossible [to beat the market] …they thought efficiency was absolutely inevitable. It was like physics; I call it physics envy. They wanted to make their subject like physics. What kind of a nut would want to make stock markets like physics? It ain’t like physics; it’s more like a mob at a football game.”
Charlie Munger
The difference shows up in an old joke. An extreme EMH-minded finance professor was walking with a student when the student pointed out a $100 bill lying on the sidewalk. The professor says, “Don’t bother picking it up; if it were really a $100 bill, someone would have picked it up already.”
A reasonable EMH finance professor, on the other hand, would say, “You better hurry and pick it up before someone else does.”
2. Markets are made of people
While markets incorporate information quickly, they don’t always do so rationally. Humans can be very irrational, especially when money is involved. Overconfidence, bias, herding, and loss aversion can all create temporary mispricings, which is why I describe markets as roughly efficient rather than perfectly efficient.
This doesn’t overturn EMH, though. Arbitrageurs work to exploit and eliminate those mispricings. And even when markets behave irrationally at a broad level, real-world limits to arbitrage often make those opportunities hard to profit from in practice. Markets can be imperfect and still very difficult to beat.
3. Markets need active investors
Active investors are essential to a well-functioning market. Without them, prices would not accurately reflect new information, stocks would drift from their underlying fundamentals, capital would be misallocated, and liquidity would evaporate. In this sense, extreme interpretations of EMH are self-defeating, because they discourage the very activity that keeps markets efficient.
“The paradox of index investing is that the stock market needs some active traders who analyze and act on new information so that stocks are efficiently priced and sufficiently liquid for investors to be able to buy and sell. Active traders play a positive role in determining security prices and how capital is allocated. This is the main logical pillar on which the efficient-market theory rests.”
Burton Malkiel
Students of finance should learn how to value businesses and compete in the marketplace, while also learning just how competitive markets are and how difficult consistent outperformance truly is.
What This Means for Investors
I believe markets are mostly efficient, that EMH is broadly true, and that index investing is the most sensible approach for the vast majority of individual investors. I don’t believe outperformance is impossible, only very difficult. A small number of investors can and do outperform through a combination of skill and luck.
Importantly, you don’t need to fully embrace EMH to see the case for index funds. John Bogle’s point holds whether markets are efficient or not:
“No matter how efficient or inefficient markets may be, the returns earned by investors as a group must fall short of the market returns by precisely the amount of the aggregate costs they incur. It is the central fact of investing.”
John Bogle
Bruce Greenwald and Malkiel make the same case from the skeptic’s side:
“We can acknowledge the effectiveness of index funds-known as passive investments…without subscribing either to the idea that the price Mr. Market offers for a security is always the best measure of its fundamental value or that no investment approaches will outperform a passive approach over time.”
Bruce Greenwald
“The occasional craziness of market prices makes a belief in EMH (even in relative efficiency) hard for many people to accept. But even nonbelievers should embrace index funds as optimal portfolio investments. Index funds should continue to outperform actively managed funds even if markets are inefficient.”
Burton Malkiel
Warren Buffett has long recommended index funds for most investors, and Charlie Munger and Peter Lynch have said similar things despite their own success in active management. Even Benjamin Graham, the father of value investing, concluded late in life that finding bargains through security analysis had become much harder. Recognizing how hard it is to beat the market doesn’t require believing it is impossible.
Markets aren’t unbeatable because of some immutable law of nature. They’re difficult to beat because the competition is relentless. Framed that way, EMH is both more accurate and more durable.
Discover more from Bryant Quick
Subscribe to get the latest posts sent to your email.

